The Bank of Japan raised its benchmark interest rate by 25 basis points to 0.75% on Friday. Governor Kazuo Ueda stated that the bank must act pre-emptively to avoid the risk of being forced to abandon yield curve control against its will. This decision follows a July move where the bank increased the overnight rate to 0.25%. The central bank also expanded its tolerance for 10-year Japanese government bond yields. It now allows these yields to fluctuate in a range of plus and minus 0.5 percentage points from the 0% target. The bank will also offer to purchase 10-year bonds at 1% through fixed-rate operations. The bank raised its median inflation forecast for fiscal 2023 to 2.5% from the 1.8% prediction from April. This policy shift tightens monetary policy while the US Federal Reserve approaches a rate-cutting cycle.
The expansion of the yield target range targets the sustainability of the current framework. Ueda noted that the bond market remains stable and that the timing for these tweaks was appropriate. He also mentioned that if inflation expectations heighten, the bank might struggle to control bond yields with market operations. This could lead to falling real interest rates and further inflation. The bank decided to make the yield curve control flexible to balance these side effects. Recent data shows that inflation has exceeded the 2% target for 15 straight months. Wages are also starting to increase after years of stagnation.
The mechanics of the yen carry trade
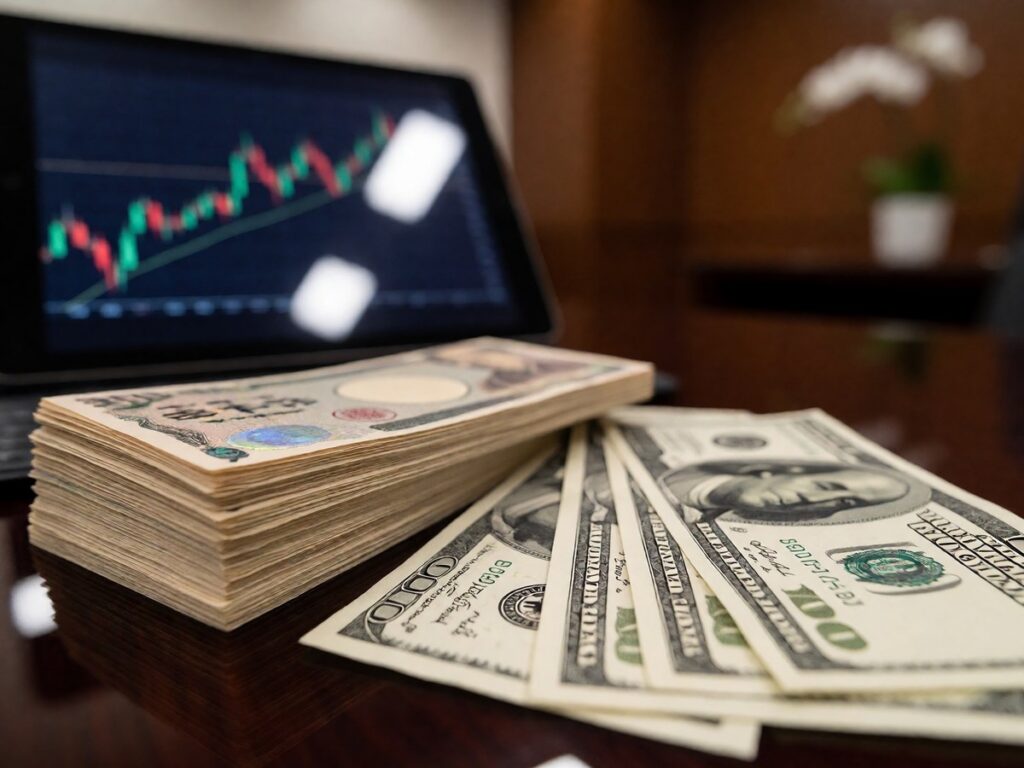
You already know how a carry trade works. Investors borrow money in a currency with low interest rates to buy assets with higher returns. The difference between these rates provides the carry, which is the expected return. In the recent past, the Japanese yen served as an ideal funding currency because interest rates remained extremely low. In July 2024, Japanese interest rates sat between 0% and 0.1%. This made borrowing yen very cheap for global investors.
Traders took this cheap yen and exchanged it for US dollars. They then invested those dollars into higher-yielding assets like US stocks. The S&P 500 rose over 16% from the start of 2024 to the end of July. Because the yen weakened significantly against the dollar during this time, investors also gained from the exchange rate move. From the end of 2023 to June 2024, the yen weakened against the US dollar by over 14%. This provided an extra layer of profit for those holding US assets.
The math changes when interest rate differentials narrow. If Japanese interest rates rise, the cost of repaying the borrowed yen increases. This can erase the profits from the interest rate spread. When the spread dwindles, investors exit their positions to avoid losses. This exit process is called unwinding the carry trade. Morgan Stanley estimates that $500 billion in outstanding yen carry positions still exist in the market.
Interest rate divergence and the narrowing spread
The primary driver of carry trade viability is the interest rate spread between Japan and the United States. The Bank of Japan is moving toward a sustained tightening cycle. In contrast, the US Federal Reserve is entering a rate-cutting cycle. This divergence implies a gradual narrowing of the interest rate spread. If Japan tightens faster than expected while the US cuts rates sharply, the spread could compress rapidly. This compression undermines the profitability of the trade and increases unwinding pressure.
The US economic data also influences this spread. In August 2024, the US employment report showed that the economy created 114,000 jobs. This fell short of the 179,000 jobs the market expected. Such a shortfall suggests a slowing US economy, which increases the likelihood of Federal Reserve rate cuts. When the Fed cuts rates, the US dollar often weakens. A weaker dollar makes it less attractive to hold US-denomely assets.
The yen moves quickly.
As the yen appreciates, investors who borrowed in yen find it more expensive to repay their loans. This increases the pressure on those still holding the position. A significant dollar depreciation prompts investors to reassess portfolio allocations. They may sell US assets to repatriate yen positions. This process strengthens the yen and accelerates the unwind.
Technology stocks as the liquidity exit
The yen carry trade functions as a form of global leverage. Large investors use borrowed yen to fund positions in high-yielding economies. This leverage often sits underneath the Nasdaq 100. Because the borrowed money helps finance richly valued technology shares, a sudden reversal in the yen can pull equities lower. This happens even if nothing changed in the companies themselves.
High-flying technology stocks are among the easiest positions to sell. When the yen strengthens and the trade turns against holders, investors must raise cash quickly. They target the most liquid and most valued names first. This can lead to a deleveraging wave across US equities. The correlation between the USD/JPY exchange rate and the Nasdaq 100 has historically been positive.
| Asset Ticker | Price Change % | Volume |
|---|---|---|
| NVDA | +1.48% | 124.70M |
| TSLA | +5.51% | 61.73M |
| MSFT | -1.22% | 507.29M |
| AAPL | -0.89% | 41.24M |
| AMZN | -2.50% | 46.09M |
The volatility in tech stocks can spike when the yen moves. In past unwinds, the yen strength coincided with a spike in the VIX volatility index. Investors often sell these positions to cover their losses.
The margin call trap
Unwinding carry trades often triggers margin calls. A margin call happens when a trade’s value falls below a required level. This forces the investor to add funds or sell assets to cover losses. Because carry trades use borrowed money, leverage amplifies the impact of market moves. The Nikkei index fell 12.4% on August 4, 2024, during a major unwinding event. This was the worst decline for the index since 1987.
The Nikkei’s 12.4% single-day plunge in August 2024 was a massive disaster for investors. This volatility in Japanese equities spilled over into global markets. The S&P 500 also dropped 3% that same day. This represents the worst one-day loss for the index in nearly two years.
The spread narrows.
When the yen rises, it creates a cycle of selling. Buying yen to close out a loss-making trade drives the yen higher. This higher yen increases the pressure on those still holding the position. This can lead to a synchronized unwinding because many trades have a homogeneous structure. Price adjustments tend to be abrupt because these trades lack buffering mechanisms.
Currency repatriation and exporter pressure
A strengthening yen threatens the profitability of Japanese exporters. Companies like Toyota and Sony sell products in dollars and repatriate their profits in yen. When the yen is strong, their earnings in yen terms decrease. The tumbling market in Tokyo can unleash a spiral.
The yen rise also affects Japanese banks. While Japanese bank shares rallied 5.3% following the recent BOJ announcement, they previously faced pressure. During the August unwind, Japanese bank shares fell by 27% in two trading days. Investors fear that lower interest rates in the US will reduce the profits of banks that lend in dollars.
Japanese investors also hold massive amounts of foreign assets. They owned $10.6 trillion in foreign assets at the end of last year. Many of these holdings are unhedged. If the yen trend has fundamentally shifted, these investors might sell US bonds in favor of Japanese bonds. This would increase the supply of US Treasuries and push US yields higher.
Monitoring the unwind risk
Traders use several indicators to assess the risk of a carry trade unwind. The interest rate spread between the US and Japan is the core measure of attractiveness. The level of the JPY exchange rate also matters. A move toward or beyond 160 yen per dollar may indicate excessive short positioning. Finally, market volatility in the VIX provides a signal of risk.
| Indicator | Current/Recent Value |
|---|---|
| JGB 10-year Yield | 1.95% |
| Projected JGB 10-year Yield | 2.25% |
| US Fed Rate Expectation | Cutting Cycle |
| Nikkei 225 (Aug 4 move) | -12.4% |
| US Jobs Growth (July) | 114,000 |
| VIX Level | 17 |
Because the yen strengthened rapidly in late July 2024, investors who had borrowed in yen found it more expensive to repay their loans, which triggered margin calls and forced a rapid unwinding of positions.
The reality of the market shift
The US Treasury market serves as a leading indicator for carry trade risk. Rapid declines in yields often reflect expectations of an economic slowdown. This signals narrowing interest rate differentials. However, US Treasury yields have remained relatively flat since mid-2023. Since early 2024, rates have stayed within a range of 3.8% to 4.7%. Even as Japanese yields rose from 1.6% to 2.4%, US rates did not spike.
This suggests that much of the carry trade has already dissipated. Many investors have already moved out of their positions. The market is in a sensitive phase. The direction of the US dollar also remains important. The dollar has stayed relatively steady since July despite rising Japanese interest rates. The dollar remains 4% above its 40-year average.
Will the Bank of Japan manage to avoid a sudden, uncontrolled abandonment of yield curve control? I think the carry trade unwind is far from over because the interest rate spread will keep narrowing.